


I have 18 years of consulting experience with banks, pension funds and asset managers as a CFA charterholder. Based on the needs of my clients, I provide advisory and project management services (in practice often a combination of both).
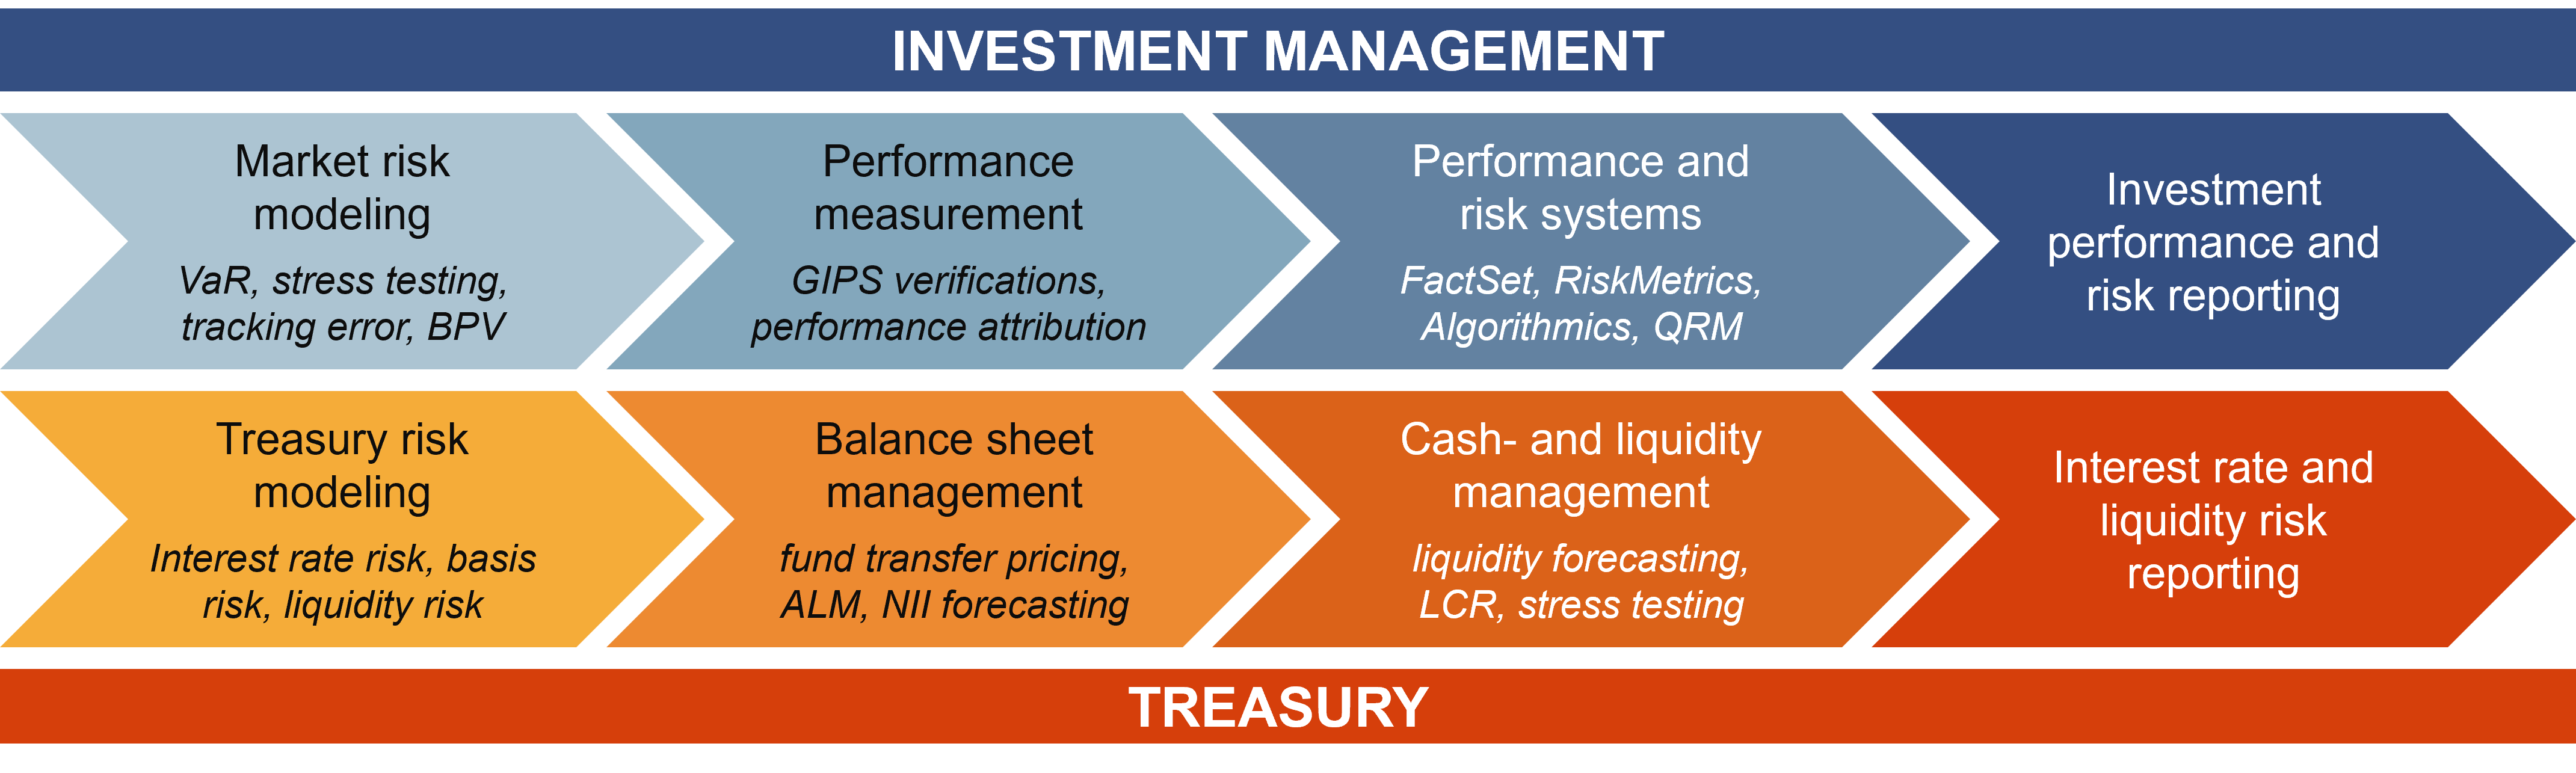
I started my career in the investment industry in 2007 at FactSet, a provider of financial data and software for portfolio analysis. In this role, I advised clients on portfolio modeling, (ex-ante) risk models, and (ex-post) performance attribution.
In 2011, I joined KPMG Advisory, advising banks, pension funds and asset managers on financial risk management (FRM). My work included the implementation of risk models and the development of investment reporting.
Since 2015, I have worked as an independent specialist in projects for banks and asset managers (click here for an overview of my projects). In addition to my day-to-day work, I serve on the Investment Performance Measurement committee of the Dutch association of investment professionals (VBA).